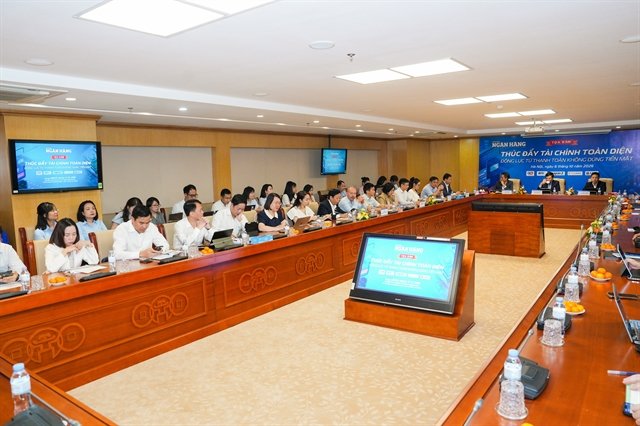
Hanoi, October 7, 2026 – The Europe Today: Cashless payments are increasingly becoming a key driver of financial inclusion in Vietnam, helping individuals and businesses gain broader access to formal financial services and supporting the country’s National Financial Inclusion Strategy for the 2026–2030 period.
Speaking at a seminar on financial inclusion, Deputy Governor of the State Bank of Vietnam (SBV) Pham Thanh Ha said cashless payment is no longer simply a change in payment methods but is becoming an important gateway to wider financial inclusion.
He noted that as individuals and businesses increasingly use bank accounts and digital payment services, financial activities are becoming more deeply integrated into everyday life and business operations. The resulting transaction data can also help expand access to appropriate financial products, including savings, credit and insurance.
Under Vietnam’s National Financial Inclusion Strategy for 2026–2030, the country aims for 95 percent of people aged 15 and above to have transaction accounts at banks or other authorised institutions by the end of the period. The strategy also targets a total value of non-cash payments equivalent to 30 times the country’s GDP, while expanding financial services to rural, remote, mountainous, border and island areas.
Ha stressed that payment and digital-finance policies should be streamlined to ensure consistency and transparency while encouraging innovation, strengthening system security and protecting users’ legitimate rights.
He also called for further development of payment and digital-finance infrastructure, greater interoperability and preparations for cross-border retail payment connectivity.
Particular attention, he said, should be given to underserved groups, including low-income communities, small and medium-sized enterprises, business households and vulnerable populations. Financial products and delivery channels should be simple, convenient, affordable and tailored to users’ actual needs.
The SBV also highlighted the importance of improving financial literacy and digital skills, alongside stronger measures to prevent fraud, protect personal data and safeguard users’ rights.
According to SBV Deputy Director of the Payment Department Nguyen Thi Thu, payment networks are expanding through new models designed to reach rural communities and groups with limited access to financial services.
As of June 30, 2026, Vietnam had approximately 5,700 payment-agent locations and 11.45 million registered mobile-money accounts, of which 6.18 million were active. A total of 5,158 mobile-money business locations were operating at commune level nationwide.
QR codes and mobile payments have also helped bring financial services closer to consumers, particularly in areas where establishing traditional physical transaction networks has been difficult.
Nguyen Thanh Tung, Deputy CEO of the National Payment Corporation of Vietnam (NAPAS), said financial inclusion should not be measured solely by the number of accounts opened, but also by whether those accounts are used conveniently, regularly and effectively in everyday activities.
He noted that digital payment infrastructure connects individuals, banks, businesses and service providers, enabling transactions to be conducted quickly and securely while reducing costs and supporting the expansion of services into rural and underserved areas.
Cashless payments recorded strong growth during the first eight months of 2026, with the number and value of transactions increasing by 34.56 percent and 13.26 percent year-on-year, respectively. Online transactions rose 46.57 percent in volume and 21.77 percent in value, while mobile payments increased 35.33 percent in volume and 23.9 percent in value.
The figures underline the growing role of digital payment infrastructure in expanding access to formal financial services and supporting Vietnam’s broader objectives for financial inclusion and digital economic development.